How SparkLMS Supports Rapid Loan Origination in High-Volume Environments

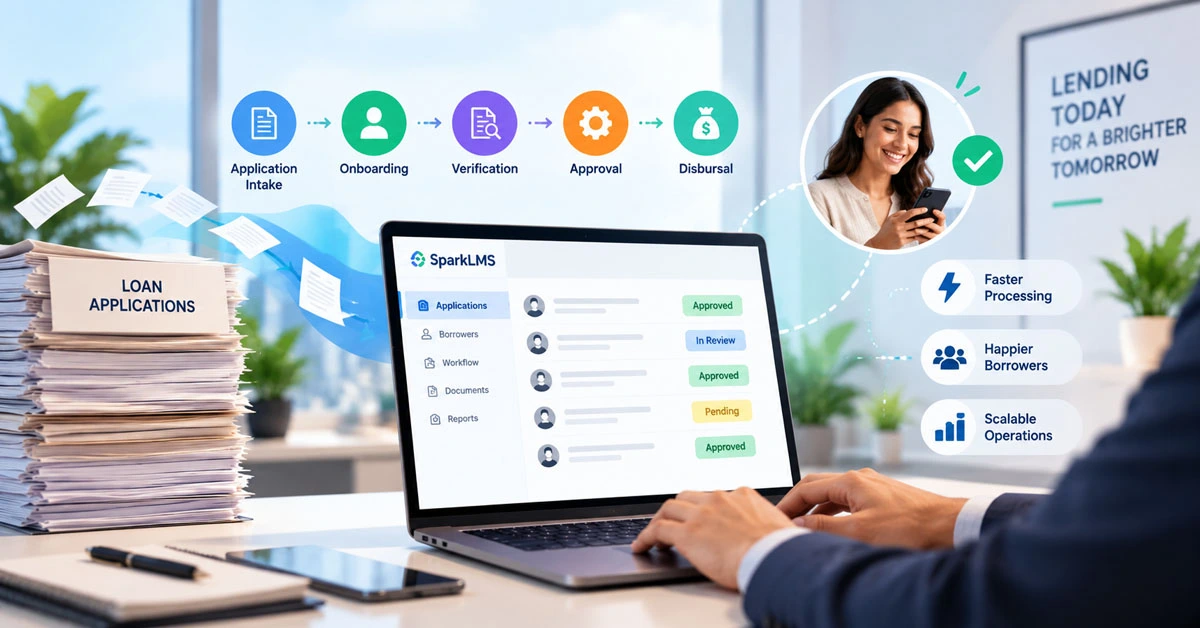
For many lenders, growth starts creating operational pressure long before it delivers business growth. As loan application volumes increase, approval delays, overloaded teams, and processing bottlenecks often follow close behind.
The problem often isn’t demand. It’s the systems behind the process. Manual verification, scattered workflows, and constant follow-ups can make it difficult to handle large application volumes efficiently.
SparkLMS helps simplify loan origination by bringing applications, onboarding, approvals, and communication into one streamlined system. By connecting the process end-to-end, lenders can process applications faster, reduce operational delays, and deliver a smoother borrowing experience even during high-demand periods.
In this blog, we’ll look at how SparkLMS helps lenders speed up loan origination while keeping operations organized and scalable.
Also Read: How SparkLMS Powers Revolving Credit at Higher Risk Tiers
Handling a steady flow of loan applications is one thing. Managing a sudden surge is completely different.
During peak lending periods, teams often have to process large volumes of applications within tight timelines while still maintaining accuracy, compliance, and borrower communication. Even small inefficiencies in the process can create delays across the entire origination cycle.
For many lenders, the challenge comes from disconnected workflows. Applications may arrive from multiple channels, documents need to be verified manually, approvals move across different teams, and follow-ups increase as queues grow longer. As volumes rise, maintaining visibility into every application becomes increasingly difficult.
This not only slows down processing but also affects the borrower experience. Missed updates, longer turnaround times, and inconsistent handling can quickly create frustration for both customers and internal teams.
Loan applications can come from multiple channels at the same time, such as websites, mobile apps, branches, brokers, and partner platforms. While this improves accessibility for borrowers, it can create operational confusion when information is spread across different systems.
Common challenges during high-volume periods include:
SparkLMS helps bring the entire application intake process into one centralized workflow. Applications, borrower information, and supporting documents can be managed from a single system instead of across disconnected platforms.
This helps lending teams:
By simplifying how applications are captured and managed, SparkLMS helps lenders improve both speed and operational control.
Borrower onboarding often slows down when teams have to manually collect documents, verify information, and follow up on incomplete submissions. During high-volume periods, even small delays at this stage can affect the entire origination timeline.
Digital onboarding workflows help reduce this dependency on repetitive manual processes while making it easier for borrowers to complete applications remotely.
With SparkLMS, lenders can streamline onboarding through:
This helps lenders onboard borrowers faster while improving data accuracy and reducing delays.
Approval delays often increase when applications move through multiple reviewers, manual checks, and disconnected approval chains. As application queues grow, assigning, reviewing, and routing applications manually can slow down decision-making significantly.
Rule-based workflows help reduce these delays by automatically routing applications based on predefined lending criteria such as:
SparkLMS also supports intelligent task distribution, allowing workloads to be allocated more efficiently across underwriting and operations teams instead of relying on manual coordination.
This helps reduce approval backlogs and maintain smoother processing during periods of increased demand.
When application volumes increase, delays become harder to identify and track across the origination process. Teams may spend more time following up internally, checking application status, and coordinating between departments instead of focusing on processing.
To manage applications more efficiently, lenders need visibility into:
SparkLMS provides centralized dashboards and reporting tools that help teams monitor application movement in real time and identify workflow slowdowns more quickly.
The platform also supports:
With better visibility into the origination cycle, lenders can respond more proactively and manage growing application volumes with greater consistency.
Borrowers don’t just expect faster approvals anymore. They also expect clarity throughout the process.
During busy lending periods, delayed responses and a lack of communication can quickly affect customer experience. Repeated follow-ups, uncertainty around application status, and unclear timelines often create frustration for borrowers as well as additional pressure on support teams.
Automated communication workflows and self-service borrower journeys make it easier for borrowers to stay updated throughout the origination process. Instead of relying heavily on manual follow-ups, they can access timely updates and application-related information more easily.
This helps lenders create a smoother lending experience while reducing unnecessary support dependency during high-demand periods.
Many legacy lending systems are built for steady workloads, not sudden spikes in application traffic. As lending demand grows, system slowdowns, accessibility issues, and integration limitations can start affecting day-to-day operations.
Cloud-based infrastructure helps lenders respond more flexibly to these shifts by supporting:
Instead of requiring major operational changes, scalable infrastructure allows lending operations to expand more smoothly as demand increases.
Loan origination often depends on multiple systems working together at the same time. Borrower verification, payment processing, customer management, and fraud checks may all happen across different platforms during the lending journey.
Without connected workflows, teams may end up:
SparkLMS supports API-driven integrations with systems such as credit bureaus, payment gateways, banking platforms, CRM tools, and identity verification providers, helping lenders create a more connected origination workflow with fewer manual touchpoints.
As loan processing speeds increase, maintaining consistency across approvals, documentation, and internal workflows becomes more challenging. This is especially true during high-demand periods where multiple teams are handling applications simultaneously.
Without structured governance measures, lenders may face gaps in compliance tracking, approval accountability, and workflow monitoring.
SparkLMS helps strengthen operational governance through features such as:
These capabilities help lenders maintain better visibility, accountability, and process control while scaling origination operations more efficiently.
By streamlining loan origination workflows, SparkLMS loan management platform helps lenders manage larger loan volumes with smoother workflows and greater operational consistency.
Its flexible workflow capabilities make the platform suitable for a wide range of lending institutions, including:
This flexibility allows organizations to adapt SparkLMS to their operational requirements while scaling lending operations more effectively.
SparkLMS brings application intake, onboarding, approvals and communication into one connected workflow. Applications from every channel land in a single pipeline, with automated verification and rule-based routing replacing manual handoffs.
Delays are usually caused by disconnected systems rather than demand itself. Manual verification, separate intake channels and approvals moving between teams without automated handoffs compound into longer turnaround across the origination cycle.
Multi-channel loan intake means accepting applications from websites, mobile apps, branches, brokers and partner platforms at the same time. It widens borrower access, but creates duplicate records and fragmented tracking when each channel feeds a different system.
Lenders reduce onboarding time by replacing manual document collection with digital workflows. SparkLMS supports online application forms, pre-filled borrower data, automatic validation, secure uploads and OCR-based document extraction and classification.
Rule-based routing automatically sends each application to the right reviewer using predefined lending criteria instead of manual assignment. In SparkLMS these include credit score thresholds, risk profile, loan product, geography and internal lending policy.
Lenders track applications through centralized dashboards showing every file's status in real time. SparkLMS covers verification, underwriting progress, pending approvals, documentation and disbursement readiness, making bottlenecks visible as they form.
Cloud infrastructure handles sudden spikes in application traffic that legacy systems, built for steady workloads, cannot absorb. It supports higher transaction volumes, distributed teams, faster integrations and reliable uptime during peak lending periods.
A loan origination platform needs to connect with credit bureaus, payment gateways, banking platforms, CRM tools and identity verification providers. SparkLMS supports these through APIs, removing repeated verification steps and manual data transfer.
SparkLMS serves consumer lenders, NBFCs and alternative lenders, fintech platforms, mortgage providers, SME lenders, microfinance institutions, credit unions and commercial lenders. Configurable workflows let each adapt the platform to its own lending model.
As loan volumes continue to grow, lenders need systems that can support faster processing without creating operational slowdowns behind the scenes.
By combining automation, centralized workflows, and connected lending operations, SparkLMS helps financial institutions manage loan origination more efficiently while maintaining visibility and control across the process.